An independent second look, on your side of the table.
When a client brings you an annuity you didn’t place, or you’re weighing a keep-or-exchange decision, get the facts verified with the carrier, the costs in dollars and a documented, plain-English analysis. We never sell products, manage money or contact your client without you.
- Contract value
- $412,000
- All-in cost
- 2.85%
- Per year
- $11,742
Illustrative contract, not a real client. Every report explains each finding in plain English.
- Yoursthe client relationship stays yours
- $0in products, AUM or commissions
- Verifiedwith the carrier, in writing
- Documentedfor your file and your client
- Flat feeper review, quoted up front
- Specialistreviews every report
Five steps. You’re in control of every one.
You decide what we review, how the findings are shared and whether we join the client conversation.
- Day oneYou order the reviewTell us the carrier, the product and what you’re trying to decide.
- Same weekYour client signs one authorizationIt lets us request contract details from the carrier. We coordinate through you.
- While the carrier respondsWe verify every figureA detailed carrier questionnaire and an in-force illustration request.
- Report readyWe score and documentThe Annuity Health Score, costs in dollars, rider mechanics and pros and cons.
- Your callYou review it togetherWith us, with your client, or both. You decide how findings are shared.
Four moments when an independent review helps.
Annual and periodic reviews
Walk in with carrier-verified numbers, including rider values and fees in dollars, instead of a statement summary.
Keep-or-exchange decisions
Document exactly what the existing contract provides so any comparison, including a proposed 1035 exchange, is apples to apples.
Inherited contracts and acquired books
Understand older contracts quickly: surrender status, legacy riders and the value that could be lost by moving.
Documentation you can keep
An independent review applied the same way every time supports your best-interest file. It doesn’t replace your firm’s compliance review.
The details statements leave out.
Every review is verified with the carrier under the client’s authorization and checked by an experienced annuity specialist.
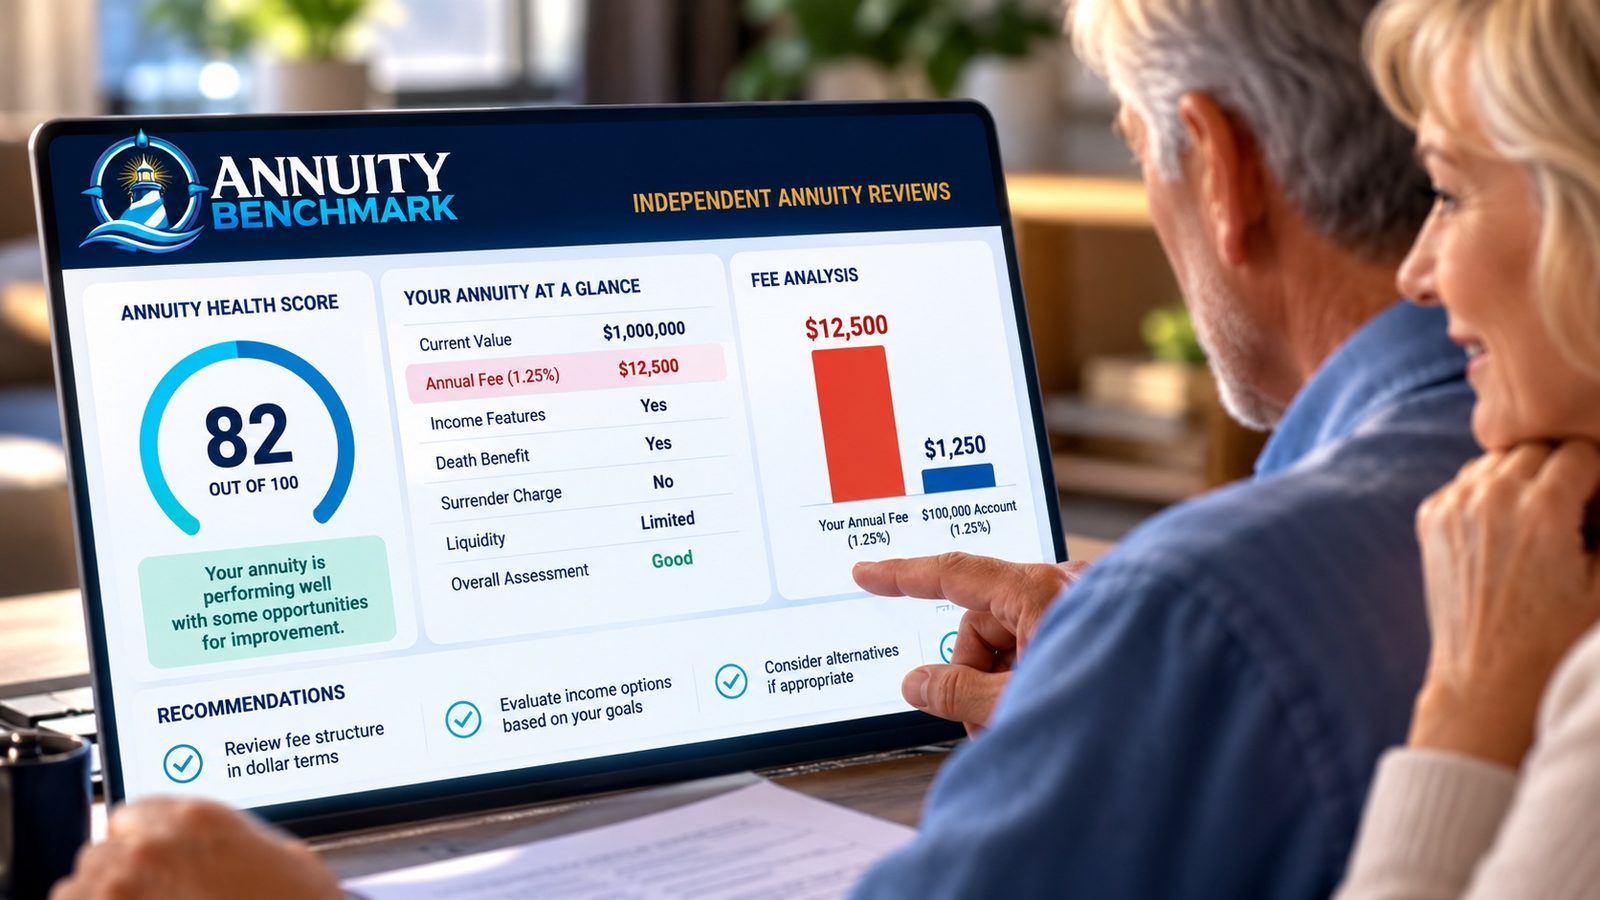
- Contract data
- Carrier-verified values, dates and contract terms, plus an in-force illustration request
- Costs
- Every identifiable charge, in dollars per year and over time
- Riders
- Benefit base, roll-ups, step-ups, re-election windows and how excess withdrawals reduce guarantees
- Liquidity
- Surrender schedule, free-withdrawal allowance and market value adjustments
- Health Score
- The 0–100 Annuity Health Score across 11 dimensions, each one explained
- Client summary
- Pros and cons in plain English, ready to share with your client
Built for the rules you already work under.
Document what the customer would give up.
When you recommend, as a registered representative, variable annuities and other securities to retail customers, an independent, carrier-verified record of the existing contract supports the analysis behind your best-interest recommendation.
Deferred variable annuity exchanges.
Rule 2330 sets suitability and supervisory requirements for recommended purchases and exchanges of deferred variable annuities, including surrender charges and the loss of existing benefits. Our contract-level documentation covers exactly those facts.
The best-interest standard for annuities.
The revised Suitability in Annuity Transactions Model Regulation sets a best-interest standard for annuity recommendations, adopted by 48 states as of 2025.1 Verified facts about in-force contracts support the required comparison.
Annuity Benchmark provides independent analysis and documentation. It is not legal or compliance advice and does not replace your firm’s written supervisory procedures.
- 2. NAIC, “Annuity Suitability & Best Interest Standard,” last updated February 10, 2025. naic.org
From one client to your whole practice.
Advisor pricing is quoted up front, per review or per arrangement. There’s nothing to buy and no assets to move.
Single reviews
Order a review whenever a client situation calls for one.
- Carrier-verified analysis and Health Score
- Client-ready summary
- A walkthrough call with you
Practice partnership
A standing arrangement for practices with several annuity clients.
- Volume pricing
- Priority scheduling
- An annual check across your annuity clients
- Joint client meetings on request
Institutional program
For firms that want a consistent, documented approach across every advisor.
- Pilot first
- Leadership reporting
- Governance and data controls
See exactly what your client would receive.
Call 803-448-4040 or email ppolito@eknox.co and we'll find a time that works.
What advisors ask us first.
A second opinion that strengthens your advice.
Thirty minutes is enough to see how it works on a real client situation.